Truck Accident Claims in Colorado

Key Takeaways

  • A truck accident claim is a personal injury claim, but it runs on a different set of rules than a car crash claim because federal trucking regulations create duties that ordinary drivers do not have.
  • More than one party is usually responsible. The driver, the motor carrier, a maintenance contractor, a cargo loader, or a parts manufacturer can each carry a share of the fault.
  • Federal law requires most interstate carriers hauling general freight to carry at least $750,000 in liability coverage, roughly seven times the amount many Colorado drivers carry on a personal auto policy.
  • Critical evidence in truck cases has a short shelf life. Driver logs, dispatch records, and engine data can be gone within months of the crash.
  • If a government-owned truck, bus, or plow caused the injury, the deadline to give written notice is 182 days, far shorter than the three-year deadline that applies to most Colorado crash claims.

What makes a truck accident claim different from a car accident claim?

A truck accident claim differs from a car accident claim in three ways: the size of the injuries, the number of parties who can be held responsible, and the body of federal safety regulation that applies to the vehicle. Everything else about the claim, including the requirement to prove negligence, works the same way it does in any Colorado personal injury case.

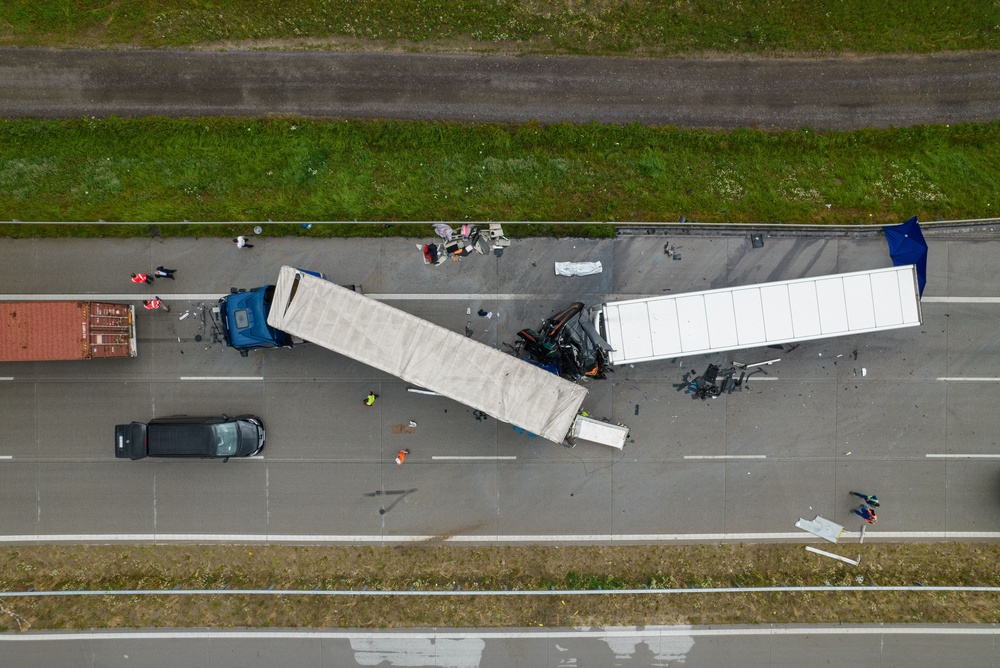
The physics explain the first difference. A fully loaded tractor-trailer can weigh up to 80,000 pounds. A midsize sedan weighs roughly 3,300 pounds. When those two vehicles meet, the injuries on the passenger vehicle side tend to be catastrophic rather than moderate: traumatic brain injury, spinal cord damage, multiple fractures, or death. That severity is why truck cases so often become wrongful death claims or lifetime care claims rather than ordinary soft tissue claims.

The second difference is the defendant list. In a two-car collision, the at-fault driver is usually the only person who owes you anything. In a commercial crash, the driver may be an employee, an owner-operator under lease, or a contractor working through a broker. Each arrangement changes who is liable in a truck accident besides the driver.

The third difference is regulation. Commercial drivers and the companies that employ them operate under the Federal Motor Carrier Safety Regulations. Those rules govern how long a driver may work, how a vehicle must be inspected, how cargo must be secured, and what records the company must keep. A violation of one of those rules is powerful evidence of negligence in a personal injury case, because the rule itself establishes the standard of care.

What counts as a commercial motor vehicle?

Federal crash reporting generally treats a large truck as any truck with a gross vehicle weight rating over 10,000 pounds, which sweeps in far more vehicles than most people expect. That category is not limited to semis pulling 53-foot trailers.

  • Tractor-trailers and semis
  • Box trucks and straight trucks
  • Dump trucks, concrete mixers, and construction haulers
  • Tanker trucks carrying fuel or hazardous materials
  • Delivery vans operating for freight and parcel companies
  • Buses, including transit, charter, and school buses
  • Municipal vehicles such as snowplows, street sweepers, and refuse trucks

The classification matters because it determines which regulations apply, how much insurance the vehicle must carry, and in some cases which court hears the case. It is worth identifying correctly at the start of a claim rather than after a settlement demand has already gone out.

What federal rules apply to truck drivers and carriers?

The rules that matter most in personal injury cases are hours of service, vehicle inspection and maintenance, driver qualification, cargo securement, and drug and alcohol testing. The Federal Motor Carrier Safety Administration publishes all of them, and the hours of service rules sit in 49 CFR Part 395.

Hours of service limits are the ones that come up most often. A property-carrying driver may drive up to 11 hours after 10 consecutive hours off duty, must finish all driving within a 14-hour on-duty window, must take a 30-minute break after 8 cumulative hours of driving, and is capped at 60 or 70 hours over a 7 or 8 day period. When a driver blows through those limits to make a delivery window, fatigue becomes a foreseeable result rather than an accident. That is the theory behind most truck driver fatigue and hours of service violations claims.

Proving a violation is a records problem, not an argument problem. Most commercial trucks now log duty status through an electronic logging device, and the engine control module records speed, braking, and throttle input in the seconds before impact. Understanding what truck black box and ELD data shows after a crash often decides whether a case settles or goes to trial.

Why does evidence disappear faster in truck crash cases?

Evidence disappears faster in truck cases because federal record retention periods are short and the vehicle itself is a business asset the carrier wants back in service. Driver logs, dispatch records, and inspection reports all have retention windows measured in months. Once the window closes, the carrier can destroy the records legally.

The tractor and trailer create a second problem. A repaired or resold truck cannot be inspected for brake condition, tire wear, or lighting failure. Neither can the cargo be weighed or re-examined once it has been offloaded. This is why preserving evidence after a Colorado truck crash is one of the first things a lawyer does, usually through a written demand sent to the carrier and its insurer within days.

The same urgency applies on the injured person’s side of the case. Photographs of the scene, the vehicles, and visible injuries are worth more than a written description months later. Our guide on what photos to take after a crash covers the specific shots that hold up in a claim, and the process for getting a copy of a Denver police accident report is worth starting early.

How much insurance does a commercial truck carry?

Federal minimums are set by 49 CFR 387.9, and they are substantially higher than personal auto minimums.

Type of carriageFederal minimum liability
For-hire interstate carrier, nonhazardous property, 10,001 lbs GVWR or more$750,000
Oil and certain hazardous materials in bulk$1,000,000
Hazardous substances in cargo tanks and certain explosives$5,000,000

The $750,000 figure was set by the Motor Carrier Act of 1980 and has not been increased since. That single fact drives a great deal of litigation behavior, because serious injury claims routinely exceed the primary policy and reach into excess layers. Understanding why truck insurance is different from car insurance explains why carriers assign a defense team to a crash scene within hours while a personal auto insurer may take weeks to assign an adjuster.

The presence of a large policy does not mean the insurer intends to pay it. Commercial insurers evaluate the same variables discussed in how insurance adjusters decide what your claim is worth, and they add one more: whether the firm representing the injured person is prepared to try the case.

What makes Colorado truck crashes different?

Colorado adds a geographic variable that most states do not have. Interstate 70 is the only east-west interstate in the state, and it climbs through sustained grades, the Eisenhower Tunnel, and weather that changes within a single hour. According to the Colorado Department of Transportation, commercial vehicles make up roughly 10 percent of traffic on I-70.

Two Colorado-specific risks show up repeatedly in commercial crash cases:

Descending grades and brake failure. CDOT’s Truck Safety Campaign fact sheet reports that Colorado has five runaway truck ramps on the I-70 Mountain Corridor, and that the Lower Straight Creek ramp on westbound I-70 near Mile Point 212 is the most heavily used runaway truck ramp in the United States. CDOT also notes that runaway ramp use peaks in summer rather than winter, which points toward brake condition and driver technique rather than snow. That distinction matters enormously in a brake failure and runaway truck ramp crash claim, because it moves the analysis from unavoidable weather toward maintenance and training.

Traction and chain requirements. Colorado’s Must Carry Chain Law covers more than 1,400 centerline miles of highway and 130 designated chain stations, 22 of which sit on the I-70 corridor. CDOT reported more than 1,300 Must Carry citations during the 2024-2025 chain season. A carrier that sends a truck into the corridor without required equipment has made a decision, and Colorado chain law violations and truck crash liability examines how that decision is used in a personal injury case.

Colorado State Patrol has also found that 65 percent of drivers who used an I-70 truck ramp had five years or less of driving experience, which raises questions about carrier hiring, route assignment, and training. Our overview of truck crashes on the I-70 Mountain Corridor goes through those theories in detail. For passenger vehicle drivers sharing the corridor, our winter driving safety tips cover the defensive habits that matter most.

What if a government vehicle caused the crash?

A crash caused by a government-owned vehicle is still a personal injury claim, but it runs under the Colorado Governmental Immunity Act, and the deadlines and damage limits are different in ways that can end a valid case before it begins.

Under C.R.S. 24-10-109, an injured person must file written notice of the claim with the correct public entity within 182 days of discovering the injury. Missing that deadline or sending notice to the wrong entity bars the claim entirely, regardless of how strong the underlying facts are.

Recovery is also capped. The Colorado Secretary of State certifies the current limits, and for claims accruing on or after January 1, 2026 and before January 1, 2030, the certified limitation on judgments is $505,000 for injury to one person in a single occurrence and $1,421,000 where two or more people are injured, with no individual recovering more than $505,000.

These rules reach snowplows, city refuse trucks, CDOT maintenance vehicles, school buses, and public transit. If you were injured by a government vehicle in Colorado, the notice clock is the first thing to address. Transit cases have their own procedural quirks, covered in our guide to RTD bus and public transit accident claims in Denver.

How does fault get divided in a Colorado truck accident case?

Colorado uses modified comparative negligence, which means an injured person can recover damages as long as they are less than 50 percent at fault, with the award reduced by their own percentage of fault. Insurance defense teams in truck cases invest heavily in shifting a percentage of blame onto the passenger vehicle driver, because every point moved is money saved.

Common defense arguments include following too closely, sitting in a blind spot, merging late, or braking suddenly. Each of those can be tested against physical evidence, and engine data frequently contradicts the driver’s account. Our explanation of Colorado’s modified comparative negligence rule walks through how the percentages actually change a settlement figure.

How long do you have to file a truck accident claim in Colorado?

Most Colorado personal injury claims arising from a motor vehicle crash carry a three-year deadline under C.R.S. 13-80-101(1)(n), which applies to tort actions for bodily injury or property damage arising out of the use or operation of a motor vehicle.

Three exceptions matter in commercial cases:

  • Claims against public entities require written notice within 182 days, well before the three-year filing deadline.
  • Wrongful death claims follow their own limitation period, which is shorter than three years.
  • Product liability theories against a component manufacturer, such as a defective products claim over a failed brake assembly or tire, are governed by a different statute.

The filing deadline is the outer boundary, not a target. Because the evidence problems described above start immediately, waiting until year two costs cases that would have been provable in month two. Our article on how long a personal injury case takes in Colorado sets realistic expectations for the timeline once a claim is underway.

What should you do after a truck crash in Colorado?

The immediate steps mirror any serious crash, with a few additions specific to commercial vehicles.

  1. Get medical care, even if symptoms seem mild. Delayed treatment is the single most common argument insurers use to discount an injury claim.
  2. Call law enforcement and make sure a report is generated.
  3. Photograph the truck’s USDOT number, motor carrier name, trailer markings, and license plates on both the tractor and trailer.
  4. Note whether the truck was carrying a placard indicating hazardous material.
  5. Do not give a recorded statement to the carrier’s insurer before speaking with a lawyer.
  6. Contact a lawyer quickly so an evidence preservation demand goes out before records age off.

Our Colorado crash checklist covers the general sequence in more detail. If the truck fled the scene or turned out to be uninsured, an uninsured motorist claim may be the path to recovery.

Why does trial readiness matter in a truck case?

Trial readiness matters more in commercial cases than in almost any other kind of personal injury claim because the defense is institutional. A motor carrier and its insurer handle these cases repeatedly, track outcomes, and price settlements according to what the opposing firm is likely to do.

Chalat Hatten & Banker has tried catastrophic injury and product cases to verdict, including a product liability judgment against Ford Motor Company and a recovery for a family struck head-on by a truck. The reason that record matters to a client is covered in our piece on why insurance companies track which law firms actually go to trial.

Frequently Asked Questions

Is a truck accident claim the same as a personal injury claim?

Yes. A truck accident claim is a personal injury claim. It simply involves an additional layer of federal regulation, more potential defendants, and larger insurance policies than a claim arising from a collision between two passenger vehicles.

Can I sue the trucking company and not just the driver?

Often, yes. A motor carrier can be responsible for the conduct of a driver acting within the scope of employment, and can also be independently negligent in hiring, training, supervision, maintenance, or scheduling.

How much is a truck accident case worth in Colorado?

No lawyer can responsibly quote a figure without reviewing the facts. Value depends on the severity and permanence of the injury, medical expenses, lost earning capacity, the available insurance, and the percentage of fault assigned to each party under Colorado’s comparative negligence rule.

What if the truck was owned by a city or the state?

The Colorado Governmental Immunity Act applies. Written notice must reach the correct public entity within 182 days of discovering the injury, and recovery is capped at the amount certified by the Secretary of State for the year the claim accrued.

Do I need a lawyer for a truck accident claim?

Commercial carriers typically deploy investigators and defense counsel to a serious crash scene within hours. An injured person acting alone is unlikely to secure engine data, driver logs, or maintenance records before those materials become unavailable.

How long do I have to file?

Generally three years for a motor vehicle personal injury claim under C.R.S. 13-80-101(1)(n). Claims against public entities, wrongful death claims, and product liability claims follow different deadlines.

Talk to a Denver truck accident lawyer

Chalat Hatten & Banker represents seriously injured people and their families across Colorado. When you call, you reach a partner of the firm. There is no fee unless we recover on your behalf. Schedule a free consultation to discuss what happened and what your options are.
Why Insurance Companies Track Which Law Firms Actually Go to Trial

Why Insurance Companies Track Which Law Firms Actually Go to Trial

Here’s something most people never hear from their insurance adjuster directly: the company doing the math on your claim already knows things about your lawyer that you might not. Specifically, whether that firm actually takes cases to trial, or whether it settles everything, no matter what.

How Claims Departments Evaluate the Other Side

Large insurance companies handle a high volume of claims and, over time, build an informal (and sometimes formal) sense of which local firms have a track record of filing lawsuits and going to verdict, and which firms settle every case regardless of the offer. Defense attorneys who represent insurers in litigation often carry this same institutional knowledge from firm to firm.

How This Shows Up in Opening Offers

When an adjuster believes a firm will accept whatever is offered, there’s less incentive to open with a strong number. When a firm has a real history of filing suit and trying cases, the calculation changes, because a lowball offer risks turning into a much larger jury verdict plus the insurer’s own litigation costs. This is a big part of why identical injuries can result in very different settlement ranges depending on who represents the client. Our guide to what a settlement mill actually looks like covers the firm-side patterns that tend to produce weaker offers.

Why This Rarely Gets Explained to Clients

It’s not exactly a secret, but it’s also not something adjusters or firms tend to bring up voluntarily. Clients are focused on their recovery and their bills, not on the negotiating dynamics happening behind the scenes. That’s part of why it’s worth asking directly about a firm’s litigation history before you hire one.

How Claims Software Fits Into This

Beyond reputation, many insurers also run claims through valuation software that estimates a case’s worth based on injury type, treatment, and other data points. A firm’s willingness to litigate is one of the few factors that can push a number meaningfully past what that software spits out. We explain how that valuation process works in how insurance adjusters decide what your claim is worth.

What to Ask Your Attorney

•        How many lawsuits has your firm filed in the past two years?

•        How many of those went all the way to a jury verdict?

•        Do local insurance adjusters and defense attorneys know your firm by reputation?

A confident, specific answer to these questions tells you a lot. For more on how to interview a potential attorney, see questions to ask a personal injury lawyer before you hire them.

A Simple Way to Picture It

Imagine two claims with identical injuries and identical medical bills, handled by two different firms. Firm A settles nearly every case within a narrow range and has not filed a lawsuit in years. Firm B has a track record of filing suit and taking cases to verdict when the offer is unfair. The insurance adjuster reviewing both claims is working from the same internal playbook in each case, but the opening number for Firm B’s client is very often higher, simply because the risk calculation is different. Nothing about the injury changed. Only the leverage did.

The Takeaway

Your case is worth what the evidence and your damages say it’s worth, in theory. In practice, who represents you affects how close the insurance company’s offer comes to that true value. That’s not a reason to panic, it’s a reason to ask the right questions before you sign with anyone.

How This Reputation Actually Gets Built

A firm doesn’t earn a litigation reputation overnight, and it isn’t something a website can manufacture. It comes from an actual track record: how many lawsuits the firm has filed, whether the same attorneys show up at depositions and mediations, and how juries have ruled when cases went the distance. Defense attorneys who represent insurance companies in Denver see the same plaintiff’s firms again and again, and they remember which ones folded under pressure and which ones didn’t. That institutional memory moves faster, and lasts longer, than most clients ever realize.

If You’re Already in the Middle of a Claim

•        Notice whether your firm has mentioned litigation as a real possibility, or only ever talks about the next settlement offer

•        Ask directly whether your file would be flagged for a potential lawsuit if the current offer doesn’t improve

•        Pay attention to how much the insurer’s number moves after your attorney pushes back; very little movement can be a sign the insurer doesn’t see your firm as a litigation risk

None of this means you need to switch attorneys mid-case. It does mean it’s worth having a direct conversation about strategy if your claim feels stuck.

This article is for general information only and is not legal advice. Specific outcomes depend on the facts of each case.

What Is a “Settlement Mill”? Warning Signs to Look For

If you’ve been hurt in a crash and started researching personal injury lawyers, you may have come across the term “settlement mill.” It sounds harsh, and sometimes people use it that way. But it also describes a real, specific kind of law firm, and knowing the signs can help you pick the right one for your case.

What Does “Settlement Mill” Actually Mean?

A settlement mill is a law firm built around speed and volume. The firm signs up a large number of clients, sends a demand to the insurance company early, and accepts whatever offer lands in a fairly narrow range. Cases rarely go to court. The whole model depends on moving a lot of files, not on squeezing the most value out of any single one.

This isn’t automatically dishonest. Plenty of people with a clear-cut, lower-value claim do just fine this way, and a fast payout can be exactly what they need. The trouble starts when a case is more complicated than that, and the firm still handles it the same way. For a full breakdown of how this model compares to a firm that’s ready to go to trial, see our guide to settlement-focused vs. trial-ready lawyers.

Six Signs You Might Be Working With One

•        Your attorney is juggling hundreds of open files, and you mostly talk to a case manager or paralegal instead

•        You’re nudged to accept the first offer, with little discussion of what your claim might really be worth

•        The firm has no real litigation team, or one too small to take more than a few cases to court each year

•        A demand letter goes out to the insurer before your treatment has even wrapped up

•        The settlement number lines up closely with what insurance claims software tends to spit out for similar injuries, rather than a number built around your specific losses

•        Filing a lawsuit is treated as a last resort to avoid, instead of a normal next step when an offer falls short

Why This Matters More for Serious Injuries

A minor fender bender with clear fault and a small medical bill can move through a settlement mill just fine. Where the model tends to fall apart is with serious injuries, long recovery times, or a case where the insurance company disputes fault. Those cases need real investigation, sometimes expert opinions, and a firm willing to file suit if the offer isn’t fair. Case timelines look very different depending on which type of firm is handling things; we cover that in detail in how long a personal injury case takes in Colorado.

Questions to Ask Before You Sign

•        How many cases has this firm taken all the way to a jury verdict in the last two years?

•        If my case doesn’t settle, who represents me in court, the person I’m talking to now, or someone else?

•        What share of your cases get resolved before a lawsuit is filed, versus after?

For a longer list of questions worth asking any firm you’re considering, take a look at our full guide: questions to ask a personal injury lawyer before you hire them.

How Chalat Law Handles This Differently

We prepare every case as though it might end up in front of a jury, even though most cases still settle. That preparation is exactly what gives our clients leverage at the negotiating table. If you want the fuller picture of why that approach tends to lead to better outcomes, our settlement-focused vs. trial-ready article walks through it side by side.

This article is for general information only and is not legal advice. Every case is different, and the best way to know where your claim stands is to talk with an attorney directly.

What Happens If Your Personal Injury Case Actually Goes to Trial?

Most personal injury cases settle before they ever reach a courtroom. That’s true across almost every law firm, including ones that are fully prepared to try a case. But “most” isn’t “all,” and it helps to know what the process actually looks like if your case is one of the ones that goes the distance.

Why Most Cases Settle, and Why Some Don’t

Trials take time, cost money, and carry some uncertainty for both sides. Insurance companies generally prefer to settle when the number is reasonable. A case usually ends up headed to trial when the insurer’s offer doesn’t come close to covering the damages, or when fault is seriously disputed and neither side will budge.

Step by Step: From Filing Suit to Verdict

1. Filing the Complaint

Your attorney files a lawsuit in court, formally starting the case. This is a routine step for a trial-ready firm, not a dramatic escalation.

2. Discovery and Depositions

Both sides exchange evidence and take sworn statements, called depositions, from witnesses, medical providers, and sometimes you. This phase usually takes the longest.

3. Mediation or a Settlement Conference

Before trial, most courts require an attempt to settle with the help of a neutral mediator. A large share of cases that were headed to trial actually resolve here, once both sides have seen each other’s full evidence.

4. Jury Selection

If mediation doesn’t work, the case moves to picking a jury from the local community.

5. Trial and Verdict

Both sides present evidence and arguments, and the jury decides fault and, if applicable, how much compensation is fair.

How Long a Trial Itself Takes

The trial portion is usually just a few days to a couple of weeks, much shorter than the litigation process leading up to it. It’s the months of discovery beforehand that take the bulk of the time, which we cover in how long a personal injury case takes in Colorado.

What Your Role Looks Like During Litigation

•        Answering written questions from the other side (called interrogatories)

•        Sitting for a deposition, where the defense attorney asks you questions under oath

•        Testifying at trial, if the case gets that far

Your attorney should prepare you thoroughly before any of this happens, so none of it comes as a surprise.

Why Being Trial-Ready Matters Even If You Never See a Courtroom

Here’s the part that surprises a lot of people: being prepared to go all the way to verdict changes how a case gets valued long before trial ever starts. Insurance companies keep track of which firms are willing to litigate and which aren’t. That track record shapes the settlement offer you get. We go deeper on this in why insurance companies track which law firms actually go to trial.

What Happens If You Win, or Lose

If the jury finds in your favor, it awards a dollar amount, and the defendant (or their insurer) is legally required to pay it, subject to appeal in some cases. If the jury finds against you, you typically recover nothing, and depending on your fee agreement, you may or may not owe money for case costs already spent. This is exactly why a trial-ready firm doesn’t take every case to trial. Cases only get pushed that far when the attorney genuinely believes the evidence supports a strong outcome for you.

Does Going to Trial Cost You Money?

Under a standard contingency fee agreement, you generally don’t pay your attorney anything unless you win. Case costs, like expert witness fees or court filing costs, are usually advanced by the firm and repaid out of any recovery. We explain how this works in more detail in contingency fees explained.

This article is for general information only and is not legal advice. Every case and every court’s process can differ somewhat.

Questions to Ask a Personal Injury Lawyer Before You Hire Them

Most personal injury firms offer a free consultation, and most people spend that time talking about their accident and their injuries, which makes sense. But that consultation is also your best chance to find out how a firm actually operates, and a few pointed questions can tell you more than any website or advertisement. Think of it less like an interview you’re being given, and more like one you’re conducting.

Why the Consultation Is Your Best Diagnostic Tool

Anyone can claim to “fight for you” in an ad. How a firm answers specific, direct questions about its own track record is much harder to fake.

The Core Questions, and Why They Matter

How many cases have you taken to a jury verdict in the past two years?

This tells you whether the firm is genuinely trial-ready or only says it is. See our article on why insurance companies track which firms actually go to trial for why this history affects your settlement even if your case never reaches a courtroom.

What percentage of your cases settle before a lawsuit is filed, versus after?

A firm that almost never files suit may be leaving value on the table in more complicated cases. Our guide to settlement mill warning signs covers this pattern in more depth.

Who handles my case if it goes to trial? Is it you?

At some firms, the attorney you meet with hands the file to someone else entirely if litigation starts. It’s worth knowing that upfront.

How do you decide when an offer is fair versus worth litigating further?

A clear, specific answer suggests a firm that actually evaluates each case individually, rather than applying the same playbook to every file.

How are your fees structured, and what happens to case costs if we don’t win?

Our article on contingency fees explained covers what to expect here and what’s reasonable to ask.

How will you keep me updated on my case?

Some firms proactively call or email with updates; others expect you to chase them down. Neither approach is automatically wrong, but you should know which one you’re signing up for.

Have you handled a case like mine before?

A rear-end collision with clear liability is a very different case from a multi-vehicle crash with disputed fault or a claim involving an uninsured driver. Ask specifically about experience with a situation similar to yours, not just personal injury cases in general.

Red Flags in the Answers You Get

•        Vague or evasive answers about trial history or verdicts

•        Pressure to sign before you’ve had time to think it over

•        An unwillingness to explain how they’d value your specific case

•        A promise of a specific dollar amount before they’ve reviewed your medical records or the details of the crash

Comparing Answers Across Firms

If you’re consulting with more than one firm, ask the same questions to each and write down the answers. Patterns tend to show up quickly, and the firm that answers clearly and specifically is usually the one that will handle your case the same way. For the fuller picture of how settlement-focused and trial-ready firms differ across the board, see settlement-focused vs. trial-ready lawyers.

A Simple Checklist for Your Consultation

•        Bring a written list of questions, don’t rely on remembering them in the moment

•        Ask who specifically will be your point of contact day to day

•        Ask to see the fee agreement in writing before you sign anything

•        Trust your gut about whether you felt heard, not just impressed

Choosing a lawyer after a crash is stressful, but it’s also one of the few decisions in this process that’s entirely yours to make. Taking a little extra time to ask the right questions tends to pay off later.

This article is for general information only and is not legal advice. Every firm and every case is different.

How Long Does a Personal Injury Case Take in Colorado?

“How long is this going to take?” is one of the first questions almost every client asks after a crash. The honest answer is that it depends, but there are patterns worth knowing so you can set realistic expectations.

Why There’s No Single Answer

Three things drive most of the variation: how long your medical treatment lasts, whether the insurance company disputes fault, and whether your case settles before or after a lawsuit is filed. Change any one of those and the timeline shifts.

A Typical Settlement Track

StageRoughly When
Claim opened with the insurerWeek 1
Medical records gathered, demand letter sentWeeks 2-6
Offer received and negotiatedWeeks 6-10
Case closes, settlement paidWeeks 10-12

This track works well for injuries that resolve quickly and clear-cut fault. It moves fast because there’s little to fight over.

A Typical Litigation Track

StageRoughly When
Investigation begins, evidence preservedWeek 1
Treatment continues, demand built around full case valueWeeks 2-12
Initial offer rejected, lawsuit filedWeeks 12-20
Discovery, depositions, mediationMonths 5-12
Settlement or trialMonth 12+

This is the path a case takes when the injury is serious, fault is contested, or the insurer’s first offer doesn’t come close to covering the damages. It takes longer, but it’s built to get a number that actually reflects the loss. Curious what the courtroom part of this actually looks like? We break it down in what happens if your case actually goes to trial.

What Speeds Things Up or Slows Them Down

•        Reaching maximum medical improvement (MMI), the point where your doctor says your condition has stabilized, since most firms wait for this before finalizing a demand

•        Whether the insurance company disputes who was at fault, which often ties back to Colorado’s comparative negligence rule

•        How responsive the insurer’s claims adjuster is, which can vary a lot company to company

If fault allocation is part of what’s dragging things out, it helps to understand how that rule works. We cover it fully in Colorado’s comparative negligence rule explained.

Setting Expectations With Your Attorney

A good attorney should be able to walk you through which track your case is likely on and why, early in the process. If a firm gives you a vague answer or seems to be settling everyone on the same fast timeline regardless of the injury, that’s worth a second look. Our article on settlement-focused vs. trial-ready lawyers digs into why that distinction matters.

Quick Answers to Common Timeline Questions

Can I settle faster if I just want this over with?

Sometimes, but it comes with a real tradeoff. Settling before your treatment is finished, or before your medical condition has stabilized, means agreeing to a number before anyone actually knows the full cost of your injury. A firm that’s honest with you will explain that tradeoff rather than just pushing for a fast close.

Does hiring a lawyer make my case take longer?

Not usually, and it often speeds things up. Insurance companies tend to move faster once they know a claim is being handled by an attorney who documents everything properly and won’t be pressured into a quick, low number.

What if the insurance company just goes quiet?

This happens more than people expect. It’s usually a sign that the insurer is waiting to see if you’ll give up or accept less out of frustration. A firm prepared to file suit has a clear next step in that situation. A firm that only negotiates does not.

This article is for general information only and is not legal advice. Timelines vary by case, and an attorney can give you a more specific estimate based on your situation.

How Insurance Adjusters Decide What Your Claim Is Worth

When an insurance adjuster gives you a number, it can feel like it came out of thin air. It didn’t. There’s a process behind it, and understanding that process can help you figure out whether an offer is fair or just a starting point.

The Role of Claims-Valuation Software

Most large insurers use software that estimates a claim’s value based on injury type, treatment codes, length of care, and similar past claims in their database. These tools are useful for the insurer because they create a consistent baseline across thousands of claims, but they don’t know anything about your specific pain, your specific job, or how a lingering injury might affect your life going forward. That’s the gap a skilled attorney is meant to close.

What These Tools Actually Weigh

•        Injury type and diagnostic codes, which sort your claim into a broad category before anything else is considered

•        Length and type of treatment, with gaps in care sometimes read as a sign the injury wasn’t serious, even when the gap was for an unrelated reason like a scheduling delay

•        Total medical billing, though the software often doesn’t distinguish well between billed amounts and what was actually paid or owed

•        Any pre-existing conditions noted in your medical history, which insurers frequently use to argue that some or all of your current pain existed before the crash

This is exactly why two people with similar injuries can get very different opening offers. A gap in treatment, an old injury mentioned in a chart from years ago, or a diagnostic code that undersells the severity of the injury can all quietly shape the number before a human even reviews the file.

The Role of Comparative Fault

Colorado uses a rule called modified comparative negligence. In short, if you’re found partly at fault for the crash, your compensation gets reduced by that percentage, and you’re barred from recovering anything if you’re found 50 percent or more at fault. Insurance adjusters know this rule well, and arguing that you share some of the blame is one of the most common ways they justify a lower offer, even when the argument is weak. We break this rule down in full in Colorado’s comparative negligence rule explained.

Why the First Offer Is Rarely the Final One

Initial offers are usually a starting position, not a final answer. Adjusters expect some negotiation, and firms with a track record of pushing back, and litigating when needed, tend to see that opening number move more than firms that don’t. We cover why that reputation matters so much in why insurance companies track which law firms actually go to trial.

How Documentation Changes the Number

•        Complete, well-organized medical records that clearly connect your treatment to the crash

•        Documentation of lost wages or reduced earning capacity, not just medical bills

•        Photos, witness statements, and other evidence gathered early, before memories fade or evidence disappears

•        Expert opinions, when needed, on long-term prognosis or future care costs

A firm that gathers this thoroughly, rather than relying on a standard demand template, tends to get better outcomes for exactly this reason.

Why Pain and Suffering Is Harder to Pin Down

Medical bills and lost wages are what’s called economic damages, and they’re relatively easy to add up. Pain and suffering, sometimes called general damages, covers the physical pain, emotional toll, and disruption to your daily life, and there’s no receipt for any of that. Adjusters often use a multiplier tied to your medical bills as a rough starting point, but that formula ignores plenty of real factors, like whether an injury has permanently limited what you can do, or whether it’s affected your relationships or your ability to work the job you had before. This is one of the areas where a generic settlement demand and one built specifically around your life tend to land on very different numbers.

The Bottom Line

An insurance company’s first number reflects its own internal math, not the true value of your claim. Knowing that going in puts you in a much stronger position to negotiate, or to recognize when it’s time to bring in an attorney who will.

What to Do If an Offer Feels Too Low

•        Ask the adjuster directly how they arrived at the number, and request it in writing

•        Compare it against your actual documented expenses and losses, not just what feels fair

•        Avoid accepting or signing anything on the spot, especially soon after the crash

•        Consider a consultation with an attorney before responding, even if you’re not sure you want to hire one

A firm that’s willing to litigate, rather than one built purely around fast settlements, is generally in a better position to challenge a number that doesn’t reflect your real losses. Our article on what a settlement mill actually looks like explains the difference in approach.

This article is for general information only and is not legal advice. It does not name specific insurance software vendors or guarantee any particular outcome.

Contingency Fees Explained: Why a Trial-Ready Firm Can Afford to Wait for a Fair Number

If you’ve never hired a personal injury lawyer before, the idea of paying “nothing upfront” can sound too good to be true. It isn’t, but understanding how contingency fees actually work explains a lot about why some firms rush to settle and others don’t.

What a Contingency Fee Is

Instead of billing by the hour, a personal injury attorney typically takes a percentage of whatever settlement or verdict you recover, commonly around one-third, though the exact number varies by firm and by whether a lawsuit is filed. If there’s no recovery, there’s no fee. This is why most people can afford a personal injury lawyer regardless of their financial situation after a crash.

A Simple Example of How the Math Works

ItemAmount
Total settlement$60,000
Attorney fee (33%)$19,800
Case costs (experts, filing fees, records)$2,500
Outstanding medical liens$8,000
What you actually receive$29,700

This is a simplified illustration, and every case looks different, but it shows why the settlement number itself isn’t the number that ends up in your pocket. Fees, costs, and liens all come off the top, which is exactly why it matters to ask about each of them upfront.

Why This Aligns Your Interests With Your Attorney’s

Because the fee is a percentage of the outcome, a bigger recovery for you means a bigger fee for the firm. In theory, this should push every firm toward maximizing case value. In practice, it plays out differently depending on the firm’s business model.

How This Plays Out Differently by Firm Type

A high-volume, settlement-focused firm often needs to resolve cases quickly to keep revenue flowing across hundreds of open files. That pressure can lead to accepting a lower number sooner rather than pushing further. A trial-ready firm handling a smaller number of cases at a time can afford to wait longer for a fair number, since its fee structure isn’t dependent on constant fast turnover. Our article on what a settlement mill actually looks like covers this volume-driven pattern in more detail.

What Costs You’re Still Responsible For

•        Case expenses like filing fees, expert witness costs, and medical record requests, which are usually advanced by the firm and repaid out of the settlement

•        These are separate from the attorney’s fee itself and should be explained clearly in your fee agreement

Medical Liens and Why They Matter

If health insurance, Medicaid, or a hospital covered your treatment, they often have a legal right to be repaid out of your settlement, called a lien. The same is true if you used medical payments coverage from your own auto policy. These liens get resolved before you see any money, and a good attorney will negotiate to reduce them where possible, since a smaller lien means more money in your pocket at the end. This step gets skipped or rushed at firms moving quickly through a high volume of cases, which is one more reason the settlement number alone doesn’t tell the whole story.

Questions Worth Asking About Fees

•        What percentage do you charge, and does it change if a lawsuit gets filed?

•        Who covers case expenses upfront, and how are they repaid?

•        Is there any circumstance where I’d owe money even if we don’t win?

For a broader list of questions to bring to your first consultation, see questions to ask a personal injury lawyer before you hire them.

Why Fee Percentages Sometimes Increase After a Lawsuit Is Filed

Some fee agreements include a step-up, for example, a lower percentage if the case settles before a lawsuit is filed, and a somewhat higher one if litigation becomes necessary. This isn’t unusual, and it reflects the added work, time, and risk involved once a case moves into active litigation. It’s still worth understanding upfront, so there are no surprises later.

What If I Want to Switch Attorneys Partway Through?

You’re generally allowed to change attorneys during a case. If you do, your original attorney is typically still entitled to be paid for the work they already put in, usually out of the eventual settlement, rather than billed to you directly. This is worth discussing with any new attorney before making a switch.

This article is for general information only and is not legal advice. Fee arrangements vary by firm and should be confirmed in writing before you sign.

Colorado’s Modified Comparative Negligence Rule and How It Affects Your Settlement

Fault in a car accident isn’t always all-or-nothing. Colorado law recognizes that, and has a specific rule for splitting the blame, and the compensation, between everyone involved. Understanding it can help explain why an insurance company is arguing the way it is about your claim.

The Rule Itself

Colorado follows what’s called modified comparative negligence. If you’re partly at fault for a crash, your compensation is reduced by your percentage of fault. If you’re found to be 50 percent or more at fault, you can’t recover anything at all. So being 30 percent at fault on a $100,000 claim means a $70,000 recovery instead of the full amount, while being 50 percent at fault means no recovery.

A Real-World Example

Your Share of FaultOriginal Claim ValueWhat You Actually Recover
10%$100,000$90,000
30%$100,000$70,000
49%$100,000$51,000
50% or more$100,000$0

How Insurers Use This Rule to Lower Offers

Because even a modest shift in fault percentage can meaningfully change what you recover, insurance adjusters frequently argue that you share more blame than you actually do. In car accident claims specifically, this might mean disputing your speed, your following distance, or whether you had the right of way, even when the evidence is fairly one-sided. This is one of the main levers adjusters use when they calculate an opening offer, which we cover more broadly in how insurance adjusters decide what your claim is worth.

Who Actually Decides the Fault Percentage

This is a detail a lot of people don’t realize until they’re in the middle of a claim: there’s no official government body that assigns a fault percentage. Early on, it’s essentially a negotiation between your attorney and the insurance adjuster, informed by the police report, photos, witness statements, and sometimes an accident reconstruction expert. If the case doesn’t settle and heads to a lawsuit, it’s ultimately a jury that decides the percentage, based on the evidence presented at trial. That’s a very different process than an adjuster simply asserting a number over the phone, and it’s part of why a firm willing to go to court has more room to challenge a fault argument than one that isn’t.

Multi-Vehicle Crashes Add Another Layer

Fault gets more complicated when more than two vehicles are involved, since Colorado’s rule requires comparing your fault against each other party individually, not just against a single combined total. It’s possible to recover from one driver even while being barred from recovering against another, depending on how fault is split up. These cases benefit especially from careful, early evidence gathering, since the more parties involved, the more room there is for finger-pointing.

Why Contesting Fault Often Requires Litigation Readiness

A weak fault argument from an insurer often gets dropped once it’s clear the case is headed to court, where a jury, not a claims adjuster, would ultimately decide the fault split. A firm that’s genuinely prepared to file suit and take a fault dispute to trial is far better positioned to push back than one that only negotiates. See our full comparison of settlement-focused vs. trial-ready lawyers for why that distinction matters here specifically.

Where This Comes Up Most Often

Fault disputes are especially common in intersection crashes, lane-change accidents, and cases involving an uninsured or underinsured driver. If your crash involved an uninsured motorist, our article on uninsured motorist claims after a Colorado crash covers how that specific situation works.

Steps That Help Protect You Against Fault Arguments

•        Take photos of the scene, vehicle positions, skid marks, and traffic signals or signs before anything is moved, if it’s safe to do so

•        Get contact information for any witnesses, since their account can matter a lot once fault is disputed

•        Avoid speculating about fault, even casually, when talking to the other driver, witnesses, or an adjuster

•        Request the police report and review it for accuracy, since errors in the initial report can carry through the entire claim

None of this guarantees an insurer won’t still argue comparative fault, but it gives your attorney real evidence to push back with rather than just your word against theirs.

This article is for general information only and is not legal advice. Fault determinations depend on the specific facts and evidence in each case.

Settlement-Focused vs. Trial-Ready Lawyers: Why the Difference Changes What Your Case Is Worth

If you’ve been hurt in a car accident in Colorado, you will eventually get a phone call from an insurance adjuster. That call almost always comes with a number attached to it. What happens next depends less on the facts of your accident than on which kind of law firm picks up the phone on your behalf.

Some firms are settlement-focused. They negotiate, they accept the insurer’s opening range with modest pushback, and they move on to the next file. Other firms are trial-ready, meaning they prepare every claim as if it is headed to a jury from the first day. Being trial-ready does not mean a firm avoids settling. Trial-ready firms settle the large majority of their cases too, just like everyone else. The difference is what that settlement looks like, because a firm willing to go the distance at trial simply has more leverage at the negotiating table.

This distinction is not just a marketing line. It changes how a case is investigated, how an insurance company responds, and, in many instances, how much compensation a client walks away with, whether the case ends in a settlement or a verdict.

Why Some Firms Are Settlement-Focused

Settling is not automatically bad, and it is not automatically dishonest. Every firm settles cases, including trial-ready ones. What makes a firm settlement-focused is that early settlement is the primary tool it relies on, rather than one option among several. There are legitimate reasons a firm leans this way:

•      Faster cash flow for the firm and the client, since litigation can take a year or more

•      Lower overhead, since preparing for trial requires experts, depositions, and courtroom staff time

•      Certainty, since a settlement guarantees a result while a jury verdict does not

•      Volume-based business models, where firms handle a high number of cases and rely on efficient turnover rather than maximizing any single case

The tradeoff is leverage. Insurance companies keep detailed records on which firms have a track record of taking cases to trial and which firms do not. Industry commentary from personal injury practices around the country consistently makes the same point: adjusters price their opening offers differently depending on whether they expect a fight.

What Does Settlement-Focused Actually Mean?

The term gets used loosely, so it helps to be specific about what it looks like in practice. A settlement-focused firm is not necessarily a bad firm, and it may still get a client a reasonable outcome. But there are a few patterns that tend to show up:

•      High case volume per attorney, often in the hundreds, which makes individualized trial preparation impractical across the caseload

•      Little to no in-house litigation department, or a small one relative to the number of active files, since most cases never require it

•      Standardized demand packages sent to insurers early, often before treatment has concluded or the full cost of future care is known

•      A negotiation range that mirrors the insurer’s own internal claims-valuation software rather than pushing meaningfully past it

•      Fee structures and internal incentives built around quick turnover, since faster case resolution means faster revenue

•      Rarely, if ever, filing suit, and treating a lawsuit as an escalation to be avoided rather than a routine next step

None of this is illegal or unethical on its own. Many clients with straightforward, lower-value claims do fine with this model, and a fast resolution can be exactly what someone needs. The risk shows up in higher-value cases, contested liability, or long-term injuries, where the case’s true worth depends on a level of investigation and negotiating leverage that a purely settlement-focused approach was never built to provide.

This is also where insurance companies do their homework. Adjusters and defense counsel track which firms have filed suit and gone to verdict in the past, and which have not. A firm’s litigation history is not a secret to the other side, even when it is not obvious to the client sitting across the table.

Why Trial-Ready Firms Approach Cases Differently

A trial-ready firm, like Chalat Law, prepares every case as though it may end up in front of a jury, regardless of whether it ultimately does. In practice, that means:

•      Building the evidentiary record early: photos, witness statements, accident reconstruction, and medical documentation gathered before the insurance company has a chance to shape the narrative

•      Retaining expert witnesses when needed, on liability, damages, or long-term medical prognosis

•      Filing suit when a fair settlement is not on the table, rather than treating litigation as a last resort

•      Valuing the case based on its full, projected worth, including future medical needs and lost earning capacity, not just the numbers an adjuster wants to discuss first

Most personal injury cases settle before trial, at every type of firm, and Chalat Law is no exception. Being trial-ready is not about avoiding settlement, it is about the position a client is negotiating from when the settlement conversation happens. A firm that has already filed suit, deposed witnesses, and lined up experts is negotiating from a position where the insurer knows a trial is a real possibility. A firm that has never taken a case to verdict is negotiating from a weaker position, and insurers price accordingly. The result, in practice, is that trial-ready firms tend to settle for more, not less often.

Why This Matters in Colorado SpecificallyColorado follows a modified comparative negligence rule: an injured person can recover damages as long as they are found less than 50 percent at fault, but their recovery is reduced by their percentage of fault. Insurance companies frequently use comparative fault arguments to justify lower offers. A firm prepared to contest fault allocation at trial is far better positioned to push back on those arguments than one that is not.

Side-by-Side Comparison

FactorSettlement-Focused FirmsTrial-Ready Firms
Primary goalClose the file quicklyRecover full value, even if it takes longer
Case preparationMinimal; built around the insurer’s first numberFull investigation, expert witnesses, trial exhibits from day one
Leverage in negotiationLimited; insurers know the firm will not go to courtStrong; insurers know a lowball offer risks a jury verdict
TimelineFaster payout, often within weeksLonger if needed, but only as long as it takes to get fair value
Case volume modelHigh volume, lower average recovery per caseSelective, higher average recovery per case
Client experience if insurer stonewallsClient is often advised to accept what’s offeredClient has an attorney prepared to file suit and pick a jury

What This Looks Like in a Real Case Timeline

Settlement-Focused Approach

•      Week 1: Claim opened with insurer

•      Weeks 2 to 6: Medical records gathered, demand letter sent

•      Weeks 6 to 10: Offer received and negotiated within a narrow range

•      Week 10 to 12: Case closes, client accepts settlement close to the insurer’s original range

Trial-Ready Approach

•      Week 1: Claim opened, investigation begins immediately, evidence preserved

•      Weeks 2 to 12: Full medical treatment documented, experts consulted, demand built around total case value

•      Weeks 12 to 20: Initial offer rejected as inadequate, suit filed if the gap remains wide

•      Months 5 to 12+: Litigation proceeds, insurer’s valuation typically increases as trial exposure becomes real, case resolves via settlement or verdict at a materially higher number

The trial-ready timeline is longer. For many clients, that tradeoff, a longer process in exchange for a stronger outcome, is the right one, particularly for injuries with long-term medical or financial consequences.

Questions to Ask Before Hiring

•      Has this firm taken cases to jury verdict in the past two years, and how many?

•      What percentage of this firm’s cases settle before a lawsuit is even filed?

•      Who handles the case if it does go to trial, and is that the same attorney I would be meeting with now?

•      How does the firm decide when an offer is fair versus when it is worth litigating further?

The answers to these questions tend to reveal, more clearly than any advertisement, which category a firm falls into.

The Bottom Line

Every personal injury case is different, and a fair, early settlement is often the right outcome for a client who wants closure and a number that truly reflects their damages. Chalat Law settles the majority of its cases too. The difference is that we prepare every case as if it may go to trial, which is precisely what gives our clients leverage when it is time to talk settlement, and the readiness to see it through if the insurance company will not offer what the case is worth.

This post is intended for general informational purposes and does not constitute legal advice. Every case is fact-specific; anyone with questions about a pending claim should consult directly with an attorney.